Same-Day Independent Legal Advice on a Director’s Guarantee
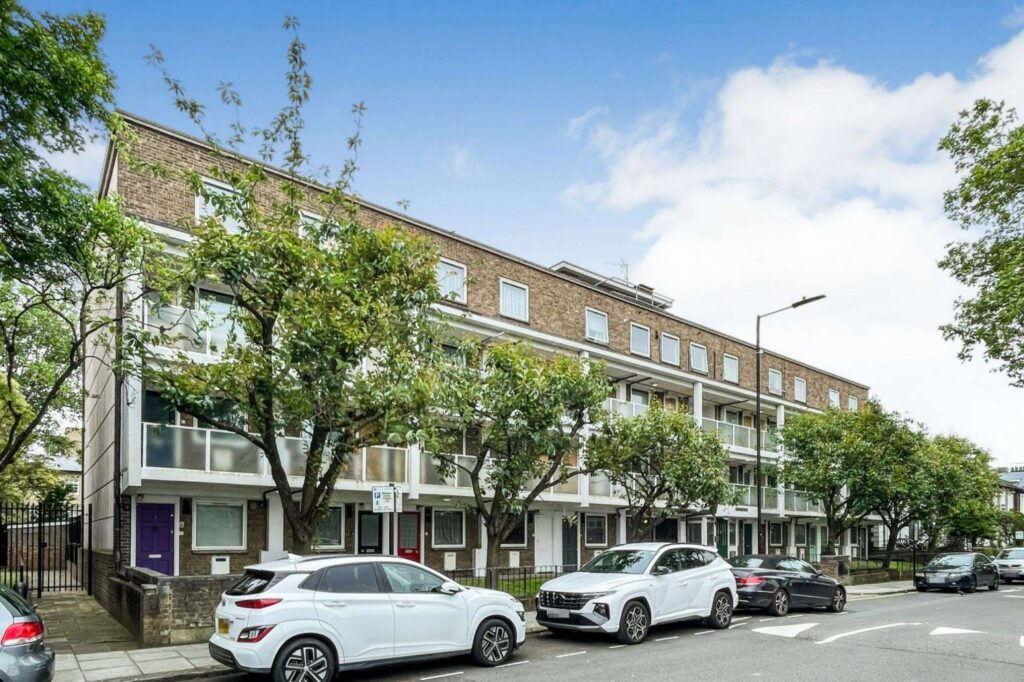
Elsie Lane Court, Westbourne Park Villas W2. A limited company buy-to-let facility, a personal guarantee, and a lender requirement that surfaced with a completion date already fixed.
At a glance
- Service
- Independent legal advice on a personal guarantee
- Location
- Elsie Lane Court, Westbourne Park Villas, City of Westminster, W2
- Client
- The director of a limited company holding a buy-to-let property
- Lender
- Fleet Mortgages
- Advised
- One director
- Outcome
- Advice given and the certificate issued to the lender the same day, at a fixed fee, in time for the scheduled completion
The situation
A director had set up a limited company to hold a buy-to-let property in W2 and arranged a facility with Fleet Mortgages. As is standard on company lending, the lender required a personal guarantee from the director — and, as a condition of accepting it, required that the director take independent legal advice on what he was signing, certified by a solicitor.
The requirement almost always surfaces late. It is not in the borrower’s mind when the offer is agreed, and it becomes urgent the moment a completion date is fixed.
Why lenders insist on it
A personal guarantee makes an individual liable for a company’s debt. It is one of the few documents an otherwise sensible person may sign without fully appreciating what it does, particularly when the company is theirs and the distinction between the two feels academic.
The courts have long recognised that a guarantee may be set aside where the guarantor did not properly understand it or was subject to pressure. A lender that takes a guarantee without ensuring the guarantor was independently advised risks holding security it cannot enforce.
The certificate is the lender’s protection. The advice is the guarantor’s.
What the advice actually covers
Most guarantors arrive expecting a signature and a stamp. The conversation that follows is usually longer than they anticipated, because a guarantee is not a formality.
The advice covers what the director is personally liable for and up to what limit; whether liability is capped or unlimited; whether it extends to interest, costs and enforcement expenses; whether the lender must pursue the company first or can proceed against the guarantor directly; what happens if the director sells his shares or resigns, and whether the guarantee survives; and what the practical exposure looks like — which, for a director whose home is his principal asset, is the question actually being asked, even when it is not asked out loud.
The director signed, having understood all of it. That is the point of the exercise.
Speed is most of the value
Same day, fixed fee, two minutes from the station
The appointment was arranged, the advice given and the certificate issued to the lender in time for the scheduled completion.
The legal content here is well settled. What a borrower needs is a solicitor who can see them today, at a price known in advance, and get the certificate to the lender in the form the lender requires. Our office is a two-minute walk from Raynes Park station and we offer same-day appointments for independent legal advice.
Common questions
What is independent legal advice on a personal guarantee?
A solicitor who does not act for the lender explains the guarantee to the person giving it, ensures they understand the liability they are taking on and that they are acting freely, and certifies that to the lender. The certificate is usually a condition of drawdown.
How quickly can it be arranged?
Same day, in most cases. The appointment itself is short; what matters is availability and getting the certificate to the lender in the form required.
Do I have to attend in person?
Many lenders require a face-to-face meeting and some will accept video. It depends on the lender’s own requirements, which are worth checking before booking.
When will I be asked for this?
On most limited company and special purpose vehicle lending — buy-to-let facilities, bridging, development finance and much commercial lending. If you have a completion date, deal with it now rather than the day before. There is no reason for it to be the thing that stops a completion, and it very often is.
Client names are not used in our case studies. Properties are identified by road, block and postcode only. Every matter turns on its own facts, and outcomes described here are not a prediction of what will happen in yours.