A Cash Purchase of a Freehold House, Completed in Three Months
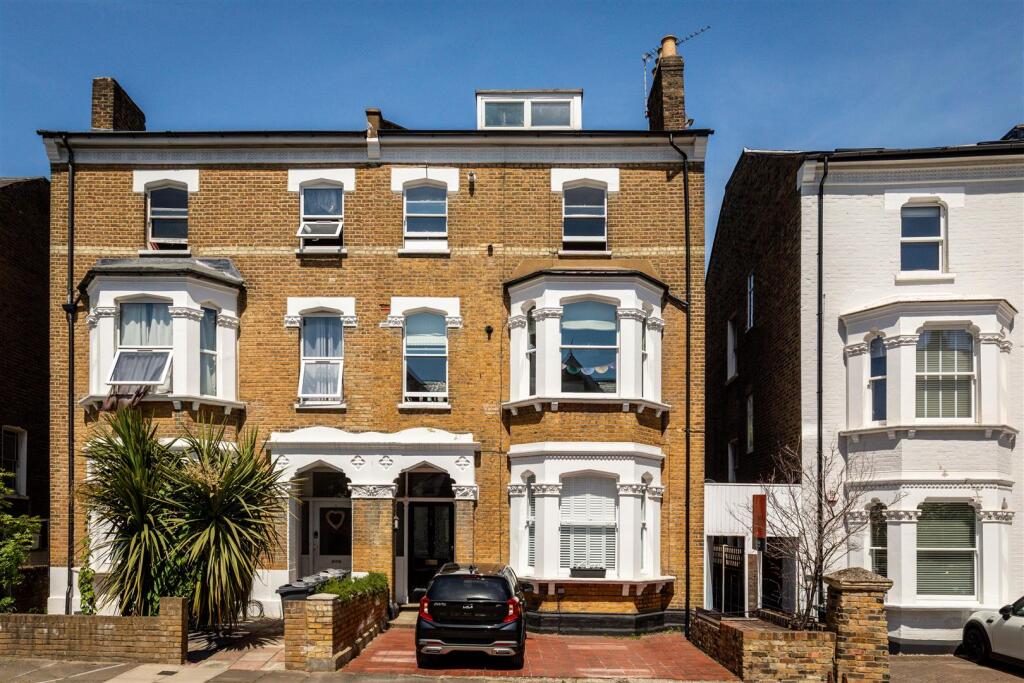
Arlington Gardens, Chiswick W4. No mortgage, no chain above, and a title that had to be examined properly rather than quickly.
At a glance
- Service
- Residential conveyancing — purchase of a freehold house
- Location
- Arlington Gardens, Chiswick, London Borough of Hounslow, W4
- Funding
- Cash purchase, with no lender involved
- Tenure
- Freehold
- Outcome
- Completed three months from instruction
What changes when there is no lender
A cash purchase removes the single largest source of delay in most transactions. There is no mortgage offer to wait for, no valuation to be booked, no lender’s conditions to satisfy and no separate set of requirements running alongside the buyer’s own.
It also removes something else, and this is the part worth saying out loud. A lender is a second pair of eyes with a commercial interest in the property being worth what is being paid and the title being good. Take the lender away and the buyer’s solicitor is the only check in the transaction.
That argues for more scrutiny on a cash purchase rather than less, which is the opposite of how these are often treated. The absence of a lender is a reason to go faster on process and no faster at all on the title.
The practical point. Buying in cash speeds up the transaction, not the investigation. Nobody else is looking at the title on your behalf.
What we look at on a freehold house
Leasehold work dominates the rest of this site, so it is worth being clear that a freehold house raises a different set of questions rather than fewer of them.
Whether the title is registered, and if not, whether the epitome of title actually proves what it needs to. Restrictive covenants, who has the benefit of them, and whether anything about the property or the buyer’s plans breaches them. Rights of way and drainage, particularly over shared or rear access. Boundaries against the plan and against what is physically there. Whether any part of the property is subject to a third party’s rights. Planning and building regulations for any works carried out. And the searches — local authority, drainage, environmental, and anything the area specifically warrants.
On a house that a buyer intends to extend or alter, the covenants and the rights matter more than anything else in the file. A covenant that is a footnote to one buyer is decisive to another.
Where a mortgage is involved
This purchase was funded in cash, which meant we could act for the buyer without any question arising about lender representation. It is worth stating our position for anyone reading this who will be borrowing.
We act on sales including mortgage redemption. On a purchase involving a mortgage we do not act for the lender. Where lender representation is required, we refer to one of our consultant solicitors who can act for both client and lender.
We say that at the outset rather than at the point it becomes inconvenient. It is a limitation on what we offer, and a buyer is entitled to know it before instructing rather than three weeks in.
When this applies to you
Buying without a mortgage
Expect a faster transaction and ask for a more thorough one. Three months from instruction to completion is a realistic timescale for a cash purchase with searches, enquiries and a proper title investigation.
If you intend to alter or extend the property, say so at instruction. It changes which parts of the title matter, and it is far better to find a restrictive covenant before exchange than after the architect has been paid.
Common questions
How long does a cash purchase take?
This one took three months from instruction to completion. Without a mortgage the timetable is set by searches, enquiries and the other side’s pace rather than by a lender.
Do I still need searches if I am not borrowing?
A lender would insist on them; buying in cash the decision is yours. We advise taking them. Without a lender, your solicitor is the only party examining the property on your behalf, and the searches are a large part of that examination.
Do you act for lenders on purchases?
No. We act on sales including mortgage redemption, and where a purchase mortgage is involved we refer to one of our consultant solicitors who can act for both you and the lender.
What are your fees for a freehold purchase?
From £1,750 plus VAT for a freehold purchase, and from £2,000 plus VAT for leasehold. Higher-value properties are quoted individually, and stamp duty land tax will apply on top depending on the price and your circumstances.
Client names are not used in our case studies. Properties are identified by road, block and postcode only. Every matter turns on its own facts, and outcomes described here are not a prediction of what will happen in yours.