An Auction Purchase in a Conservation Area, Refinanced After Refurbishment
Tennyson Street, Battersea SW8. Bought at auction for cash by a limited company, refurbished, then refinanced — with independent legal advice provided for the borrower.
At a glance
- Service
- Auction purchase of a leasehold flat, with independent legal advice on the later refinance
- Location
- Tennyson Street, Battersea, London Borough of Wandsworth, SW8
- Property
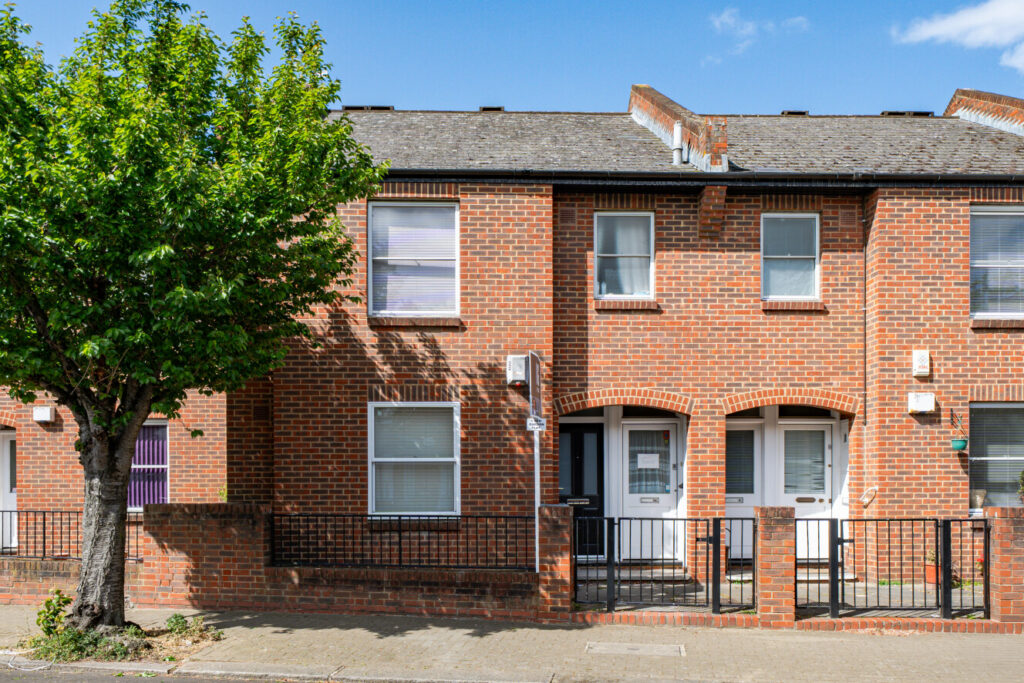
- Period ground floor flat within the Diamond Conservation Area, near Queenstown Road
- Tenure
- New 125-year lease granted on completion
- Client
- A limited company
- Funding
- Cash on completion, followed by a term loan after refurbishment, with independent legal advice provided for the borrower
What a conservation area does to a refurbishment plan
The flat sits within a conservation area, which matters for a buyer intending to refurbish and refinance rather than simply live there.
Conservation area designation does not prevent work. What it does is narrow permitted development and bring things within planning control that would be unremarkable elsewhere — replacement windows, changes to the front elevation, roof alterations, satellite dishes, sometimes even the boundary treatment. Demolition of anything substantial requires consent in its own right.
For a ground floor period flat, the practical effect concentrates on the front: what can be changed, what has to be like-for-like, and what needs an application before it can be touched.
A buyer whose figures assume a full replacement of the front windows needs to know this before bidding, not after. It is a legal pack point rather than a planning consultancy point — the designation is a matter of record, and identifying it early is part of the review.
The practical point. Check the designation before you bid, particularly if your numbers depend on external works. Inside a conservation area, permitted development is not what it is elsewhere.
The new lease, and why it was read carefully
The sale was structured with a new 125-year lease granted on completion rather than an existing lease being assigned. That is welcome — a fresh long term rather than an inherited short one — but it means a lease has been drafted, and a drafted lease has to be read.
On a flat being bought to refurbish and let, the provisions that matter most are the ones a residential buyer might skim: what alterations are permitted and on what terms, whether subletting is allowed and whether the landlord’s consent is required, how the service charge is apportioned, and what the ground rent provisions say.
That last one is not optional to check. Since 30 June 2022 a long residential lease of a single dwelling granted for a premium may reserve no more than a peppercorn, and old precedents still circulate. We have seen a rent inserted into a new lease on another auction purchase in this portfolio, and had it removed before completion.
Buying through a company, and what follows
The client was a limited company, which is the usual structure for a buy-to-let acquisition and carries consequences beyond the purchase itself.
The flat was bought with cash, refurbished, and then refinanced on a term loan. When a company borrows, lenders almost invariably require personal guarantees from the directors — and, as a condition of accepting those guarantees, certified independent legal advice from a solicitor who is not acting on the transaction.
We provided that advice for the borrower. Because the requirement was anticipated rather than discovered at drawdown, it did not become the thing holding up the facility, which is what usually happens.
Stamp duty land tax on a company acquisition of residential property is charged at higher rates than for an individual, and that should form part of the bidding arithmetic rather than a surprise afterwards.
When this applies to you
Buying at auction to refurbish and refinance
Three things to establish before you bid. What the planning designation permits, because it governs what your refurbishment can actually include. What the lease says about alterations and subletting, if a new one is being granted. And what your exit finance will require of you, because personal guarantees and independent legal advice arrive at the end of the process but can be planned for at the start.
Common questions
Does a conservation area stop me refurbishing?
No, but it narrows permitted development and brings external changes within planning control — windows, front elevation, roof alterations and similar. Internal work is generally unaffected. Establish the position before bidding if your figures depend on external works.
Can a new lease granted at auction include a ground rent?
Not where it is a long residential lease of a single dwelling granted for a premium on or after 30 June 2022 — it may reserve no more than a peppercorn. Old precedents still circulate, so the draft should be checked.
Why will my lender want independent legal advice?
Because company lending is usually supported by personal guarantees from the directors, and a guarantee is more difficult to challenge later if the guarantor took independent advice. The certificate is normally a condition of drawdown.
Is stamp duty higher for a company?
Higher rates apply to company acquisitions of residential property. The figure should be built into your bidding arithmetic, and we can confirm the rate applicable to your circumstances before the auction.
Client names are not used in our case studies. Properties are identified by road, block and postcode only. Every matter turns on its own facts, and outcomes described here are not a prediction of what will happen in yours.